The home goods industry maintains its strength in retail
The International Housewares Association (IHA) MarketOutlook 2026 report analyzes market outlook and reveals consumers' key purchasing intentions for the coming year, with health and wellness among the trends that continue to gain prominence.


Home goods continue to be a reliable source of general merchandise sales, and consumers are especially focused on health and wellness, according to the MarketOutlook 2026 report from the International Housewares Association (IHA). This second installment of the IHA State of the Industry Report 2026, which features exclusive data from consulting firm Morning Consult on purchase intent for the coming year, was published today on HomePageNews.com.
“At a time when many shoppers are re-evaluating and adjusting their spending, MarketOutlook offers a detailed look at what types of home products consumers expect to buy over the next year, as well as where, why and for how much,” he noted. Derek Miller, president and CEO of it HAVE. “It is a valuable resource for both home furnishings suppliers and retailers in defining and refining their product development, marketing and merchandising strategies.”
The report divides the industry into 15 categories and offers comprehensive data on what products consumers expect to buy in the next 12 months, the key factors influencing their purchasing plans and the most likely sales channels. The survey also reveals how much more (if any) consumers are willing to pay for different types of products.
Main conclusions
MarketOutlook's main findings include:
-
Home products and goods continue to be a reliable driver of general merchandise in the retail sector. At least 50% of respondents said they are “very likely” or “somewhat likely” to purchase products from most major industry categories.
-
The three categories with the highest purchase intention are related to health and well-being. Cleaning supplies ranked first (67% very or somewhat likely), followed by home health care products (65%). Personal care and beauty, which younger generations often associate with self-care and mental well-being, came in third with a 60% likelihood to purchase.
-
Replacing an old or broken product is the main reason for purchasing in all categories. Purchase intention is higher among adults aged 18 to 44 than among those over 45.
-
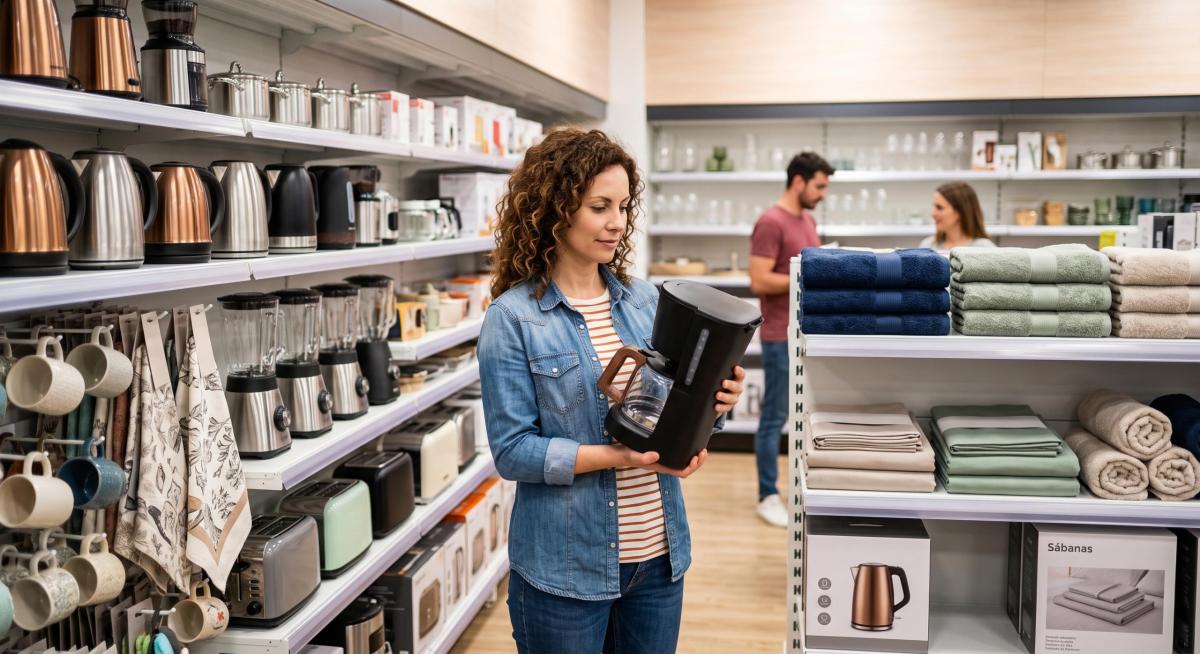
Regarding inflation, potential buyers are willing to pay more for some types of products. The top categories in which consumers would agree to pay a higher price include outdoor gear (66%), luggage and travel accessories (64%), HVAC and home environment (64%), floor care appliances (63%), and small kitchen appliances (63%).
Specific data by category
MarketOutlook also includes detailed information for each category on various topics, such as the most popular products, preferred materials, and chosen purchasing channels.
A sample of the specific findings includes:
-
In the cooking items category (pots, pans, etc.), the basic need to replace an old or broken product is the main motivation for purchasing a new one (40%). However, the ability to get new features is the main reason for another 23%, one of the highest rates among kitchen categories.
-
Having a preferred brand is the main attribute that would motivate consumers to pay more for a kitchen appliance (75%). This is followed by non-stick surfaces on parts that require cleaning (71%), the product being made in the USA (70%), lower energy consumption (69%), stainless steel finish (69%) and a longer warranty (68%).
-
In the storage and organization category, food storage containers (tápers) continue to lead purchase plans (40%). Also popular are closet organizers (38%), laundry baskets (35%), organizing boxes (29%), and kitchen or pantry organizers (29%).
-
Despite the rise of eco-friendly materials, convenience sometimes wins out in the cleaning category: 40% said they plan to purchase cleaning supplies with disposable cloths.
IHA State of the Industry Report 2026
The IHA State of the Industry Report 2026 is the industry's comprehensive market study that examines U.S. retail sales volume by category, sales percentages by channel, consumer purchase intent, and lifestyle values and motivators. The report is published in three installments:
-
Parte 1: MarketScope — Sales data for the total US home goods market and key categories, as well as sales by retail channel. The data is obtained through the IHA's alliance with the market research and analysis firm Circana.
-
Parte 2: MarketOutlook — A detailed analysis of consumer purchase intent for the coming year, as well as key product features, benefits, and other factors that guide their decisions. It has exclusive data commissioned by the IHA from Morning Consult.
-
Part 3: MarketWatch — Research and indicative analysis of the main values and trends that influence consumer attitudes and purchasing behavior. It has exclusive data commissioned by the IHA from Springboard Futures.
Methodology and complete data
Complete data, charts and analysis for MarketOutlook 2026 can be found at HomePageNews.com. The report is free and available to all industry professionals.
The report's consumer survey was conducted for the IHA by Morning Consult during the first quarter of 2026, with a sample of 2,201 adults. Interviews were conducted online and results were weighted to approximate a representative demographic sample based on age, gender, race, educational level, and region. The results have a margin of error of plus or minus two percentage points.
The 15 categories analyzed are: baking items, cooking items, kitchen utensils, glasses and cups, tableware, cutlery, small kitchen appliances, home storage and organization, personal care, air conditioning and home environment, cleaning items, floor care appliances, luggage and travel items, outdoor items and home health care products.

Latest news
Outstanding sector